Buy-and-build has become a major value creation strategy for many Private Equity firms and ambitious businesses.
The logic is compelling: accelerate growth, gain scale, expand into new markets, improve margins, strengthen competitive positions and potentially benefit from higher valuation multiples.
But buying businesses and making them successful together are two very different things.
Acquisitions may be justified by financial models and strategic plans. Their success ultimately depends on the ability of leaders, teams and organizations to make the combination work.
And some of the biggest integration problems begin well before closing.
The acquirer may not be ready to absorb another business. Both sides may have different expectations of what comes next. Key people may have no intention of staying. Or integration decisions may undermine some of the very strengths that made the target attractive.
The objective is not to integrate as quickly or as completely as possible. It is to protect what creates value, strengthen what needs to improve and build a more successful business together.
This requires understanding the human, leadership and organizational conditions of success as early as possible, ideally before the acquisition.
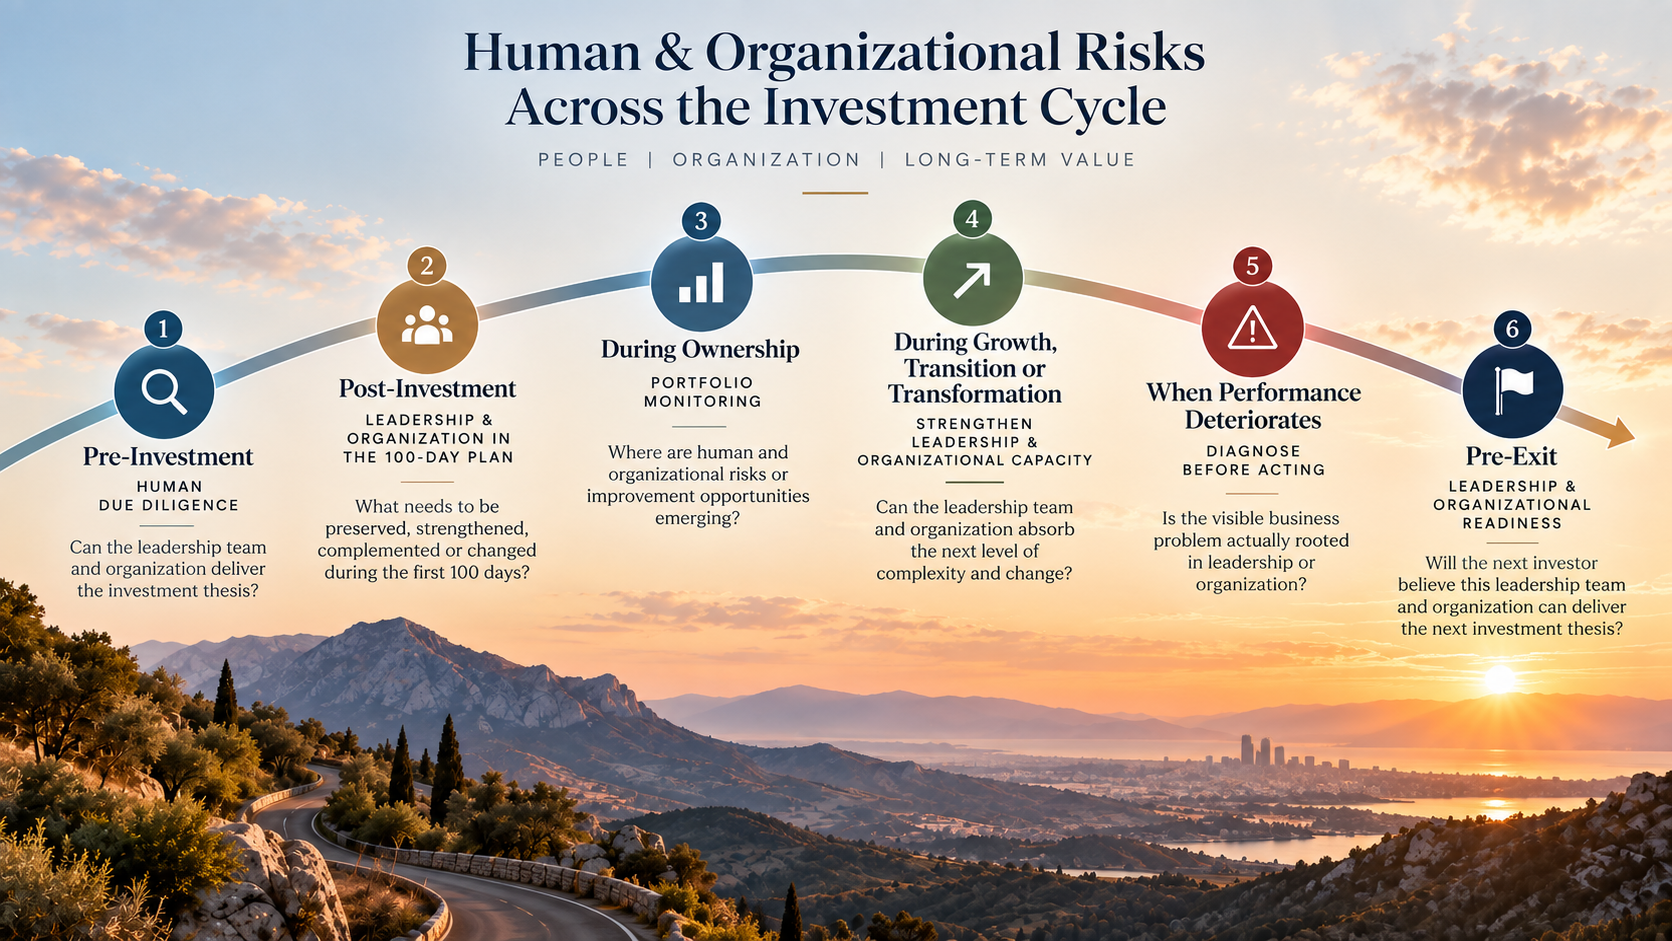
A structured Human Due Diligence or Organizational Assessment can help investors and leadership teams identify the risks, opportunities and decisions that will shape the success of the combination.
Here are eight questions worth addressing.
1. Do both sides really share the same vision of the future?
Two companies can agree on an acquisition without agreeing on what comes next.
The acquirer may envision a fully integrated group with common systems, processes and management.
The acquired company’s leaders may imagine continuing to run their business with considerable autonomy, supported by a stronger shareholder.
Both may genuinely believe the deal is attractive. Both may even think they share the same vision.
Until integration begins.
These differences can be difficult to resolve after closing, particularly when expectations were never made explicit.
Beyond the strategic rationale and expected synergies, investors and leadership teams need to clarify:
- What is the combined business expected to become?
- What will each company contribute to its success?
- How much integration is actually required?
- What autonomy will the acquired business retain?
- What will change for its leaders, employees and customers?
Some of the most important integration decisions are made before the acquisition, when both sides still have the opportunity to align their expectations.
2. Which decisions need to be made early, and which should wait?
Integration requires decisions. But making them too quickly can be as damaging as making them too late.
Who will lead the combined organization? Which brand will be retained? Which functions will be centralized? Which systems will become the standard? Which roles will disappear?
These decisions may ultimately be necessary.
But the acquirer may not yet understand how the target really operates, where its strengths lie or what makes its people and customers successful.
A decision that appears obvious from the outside can have consequences that take years to correct.
Some matters require immediate clarity: governance, decision rights, integration responsibilities, critical retention actions and business continuity.
Other decisions may benefit from more time, better information and experience working together.
Leadership appointments, organization design, branding and functional consolidation should not automatically be decided before the businesses have had an opportunity to understand each other.
An Executive Assessment or Executive Team Assessment can help inform important leadership decisions.
Move quickly where clarity is essential. Take the time to understand where decisions could permanently affect the value of the business.
3. What should be integrated, and what should be preserved?
Integration does not necessarily mean standardization.
The acquiring company may be larger, better capitalized and more experienced in acquisitions.
But the target may have a stronger brand, more effective processes, better customer relationships or a management culture that delivers superior results.
And its people know it.
Ownership does not automatically make the acquirer’s way of working the best one.
Imposing common processes or structures without understanding these differences can damage the very capabilities that justified the acquisition.
The challenge is to distinguish between three types of decisions:
- Integrate: where common systems, processes or capabilities genuinely improve performance or enable synergies.
- Align: where coordination, shared objectives and clear interfaces are sufficient.
- Preserve: where autonomy, expertise, customer proximity or distinctive ways of working contribute to the target’s success.
This assessment should cover the main functions and interfaces of the combined business, including commercial activities, operations, finance, technology, HR and governance.
It should also work in both directions.
Sometimes the acquired company has practices that the wider group would benefit from adopting.
The question is not which company’s model should prevail. It is which combination of strengths will create the most value.
4. Who is critical to future success, and who actually wants to stay?
Much of a company’s value depends on people whose contribution is not always visible in an organization chart.
They may hold critical customer relationships, technical expertise, operational knowledge, commercial capabilities or informal influence.
In many acquisitions, investors expect these same people to continue growing the business and delivering the value creation plan.
But an acquisition can fundamentally change their professional situation.
Some may welcome new opportunities. Others may lose autonomy, influence or motivation. Some may simply have different plans for their future.
Understanding these intentions as early as possible is essential.
Integration preparation should identify:
- Which people and capabilities are critical to preserve.
- Who is willing and able to take on broader responsibilities.
- Who may leave or become disengaged.
- Where critical knowledge and customer relationships are concentrated.
- Which roles and capabilities will be required in the future organization.
Not everyone will stay. Not everyone will embrace the change. Some departures and difficult decisions may be unavoidable.
The objective is not to preserve every role or satisfy everyone.
It is to anticipate these changes, manage them responsibly and ensure that the combined business retains the people and capabilities required to succeed.
You can acquire a company. But you cannot automatically acquire people’s commitment to making it successful.
5. How will the acquisition affect motivation, trust and business continuity?
For shareholders, an acquisition may represent an attractive investment and a new growth opportunity.
For the acquired company’s employees, it can feel very different.
They may face uncertainty about their jobs, managers, responsibilities, autonomy, culture or future opportunities.
Even when the acquisition makes perfect strategic sense, it can create anxiety, frustration and resistance.
These reactions should not automatically be interpreted as an unwillingness to change.
Some concerns are entirely legitimate.
And there is a business consequence.
The company is often expected to continue serving customers, growing revenues and delivering its financial targets while its people are dealing with substantial change.
Moving too quickly can disrupt operations, weaken customer relationships and exhaust management teams.
Sometimes the immediate priority after closing should be to stabilize the business.
Give people time to understand what is happening. Protect critical activities. Clarify what will and will not change. Allow the two organizations to get to know each other and learn to work together.
This does not mean avoiding difficult decisions or postponing integration indefinitely.
It means recognizing that preserving business performance and maintaining people’s willingness to contribute are essential conditions for successful integration.
6. Is the acquiring platform really ready for another acquisition?
Considerable attention goes into assessing the target.
But how much attention goes into assessing the acquirer?
Having the financial capacity to acquire a business does not necessarily mean having the leadership and organizational capacity to integrate it successfully.
The acquiring company’s management team may already be overstretched. Its organization may be struggling with complexity. Previous acquisitions may not yet be fully integrated.
Critical functions may lack the resources, capabilities or maturity required to absorb another business.
Some expected synergies may therefore be unrealistic, not because of weaknesses in the target, but because the acquirer is not ready to deliver them.
And readiness also requires an honest understanding of the acquirer’s own weaknesses.
Where does the platform genuinely perform better? Where does it have something valuable to bring to the target? And where should it be prepared to learn from the company it is acquiring?
This matters particularly in accelerated buy-and-build strategies.
Every acquisition changes the platform that must absorb the next one.
The leadership team and organization that successfully completed the first acquisition may not have the capacity to manage the fifth or sixth in the same way.
A broader Organizational Assessment can help investors and Boards assess whether the platform has the leadership strength, organizational maturity and execution capacity required for its next stage of growth.
Buyer’s readiness deserves as much attention as the quality of the target.
7. How will the two organizations learn to work together and create value?
A shared strategy does not automatically create effective cooperation.
The two businesses may have very different ways of making decisions, managing people, serving customers, allocating resources or resolving disagreements.
These differences are not necessarily problems.
They become problems when they prevent people from working together or undermine execution.
Integration therefore requires more than defining reporting lines and common processes.
It requires building relationships, clarifying responsibilities and creating practical opportunities for teams to cooperate.
It also requires a coherent approach to customers. The combined organization should be clear about what it offers, how its businesses work together and how the acquisition improves its value proposition.
One particularly effective way to build confidence is to generate early, tangible successes.
A new customer won jointly. A commercial opportunity brought by the acquirer to the target. A capability shared across businesses. An operational improvement that benefits both sides.
These early wins do more than generate financial value.
They demonstrate that the acquisition can create opportunities for both organizations.
They encourage cooperation, build trust and help people feel that joining forces was the right decision.
The acquirer should create value for the target, just as the target should contribute to the success of the wider group.
Integration becomes easier when people experience the benefits of working together rather than simply being told about them.
8. Are incentives, priorities and integration decisions supporting the same objectives?
Even when the strategic vision is shared, incentives and day-to-day priorities can pull people in different directions.
At leadership level, earn-outs, equity arrangements, bonuses, P&L responsibilities and synergy targets should support the intended integration model.
It makes little sense to ask executives to maximize group synergies while rewarding them exclusively for protecting the performance of their own business.
But alignment must extend beyond financial incentives.
Shareholders may see growth, synergies and value creation.
Managers and employees may see additional work, more reporting, reduced autonomy and uncertainty about their future.
If the people expected to deliver integration see mainly costs and disruption, their reluctance should not be surprising.
The benefits of the combination need to become meaningful at different levels of the organization.
They may include new responsibilities, better tools, stronger capabilities, career opportunities, access to customers or simply a more successful business.
At the same time, some difficult changes will be necessary, and not everyone will benefit equally.
The challenge is to make the choices clear, manage their consequences and maintain sufficient alignment and commitment to deliver the strategy.
Successful integration requires more than agreement on the investment thesis. It requires the people responsible for execution to have reasons and incentives to make it work.
Preparing integration before closing, and adapting after
These eight questions are not simply matters to address once the acquisition has been completed.
Many should be explored during due diligence, when investors and management teams still have the opportunity to identify risks, clarify expectations and prepare important decisions.
The objective is not to design every detail of the future organization before closing.
It is to understand the conditions required for success and avoid decisions that could be difficult to reverse.
Before the acquisition
Assess the readiness of the acquiring platform, understand the target’s leadership and organization, clarify the vision of the combined business and identify critical people, capabilities and potential sources of friction.
Challenge the assumptions behind the integration plan, including expected synergies, management appointments, organizational changes and the degree of integration required.
Some issues may affect the investment decision itself. Others may require specific commitments or preparation before closing.
During the first months
Protect business continuity, stabilize critical activities and establish clear governance and responsibilities.
Give both organizations opportunities to understand each other and develop effective working relationships.
Prioritize the changes that are essential to performance and the integration initiatives that can demonstrate tangible benefits.
Not every function needs to be merged immediately. Not every process needs to be standardized.
Some changes can wait until the business is ready to absorb them.
Throughout integration
Continue testing the assumptions behind the original plan.
Some initiatives will work as expected. Others will prove more difficult, create unintended consequences or threaten existing strengths.
New opportunities may also emerge as teams learn from each other.
The integration roadmap should therefore remain flexible.
The objective is not to execute the original integration plan at all costs. It is to make the acquisition successful.
That may require accelerating certain initiatives, postponing others or reconsidering decisions that no longer make sense.
See also Build-up Integration for WINGMIND’s approach to assessing and preparing these challenges.
Four dimensions that determine integration readiness
Behind these questions are four interconnected dimensions that investors and leadership teams need to understand.
Leadership & Governance: Are the right leaders in place? Can they work together, make decisions and manage the additional complexity? Are responsibilities and decision rights clear?
Strategic Clarity & Alignment: Do the investor, acquirer and target share a sufficiently clear understanding of what the combination should achieve and how value will be created?
Organizational & Operational Effectiveness: Can the acquiring platform and target execute the plan while maintaining business performance? What needs to be integrated, strengthened or preserved?
Culture, People & Readiness: How will the acquisition affect motivation, trust, cooperation and the willingness of key people to contribute to the future organization?
These dimensions are closely connected.
What appears to be cultural resistance may reflect unclear governance. What looks like poor management performance may result from organizational overload. Difficulties in capturing synergies may reveal weaknesses in the acquiring platform rather than in the target.
Understanding the underlying causes is essential to making the right decisions.
The objective is not integration. It is value creation.
Successful buy-and-build strategies are not measured by how quickly acquired businesses adopt common systems, processes or structures.
They are measured by whether the combination creates a stronger, more competitive and more successful business.
That means continuing to serve customers, growing revenues, improving performance, realizing the right synergies and strengthening the capabilities of the combined organization.
It also means preserving what already works.
Some integration risks can be anticipated before the acquisition. Others will emerge as the two businesses begin working together.
There will be difficult decisions, inevitable disruption and sometimes people who choose not to continue the journey.
But there should also be opportunities for both sides to become stronger, learn from each other and experience the benefits of the combination.
The earlier investors and leadership teams understand what could prevent success, the more options they have to protect value and make the acquisition work.
This is where a structured Human Due Diligence or Organizational Assessment can make a difference, by identifying the leadership, human and organizational factors that will influence the success of the deal.
And when difficult decisions or organizational changes are required, CEO & Board Advisory can help investors and management teams turn these insights into action.
Related approaches
Human Due Diligence ·
The Human Side of Build-ups ·
Build-up Integration ·
Organizational Assessment ·
Executive Team Assessment ·
Executive Assessment ·
CEO & Board Advisory
Founder of WINGMIND, David Chouraqui is an Operating Advisor & Executive Coach to PE/VC investors, boards and CEOs. A former private equity investor and entrepreneur, he specializes in Human Due Diligence, leadership assessments, organizational diagnostics and CEO & Board Advisory, helping organizations strengthen the human drivers of execution and value creation.